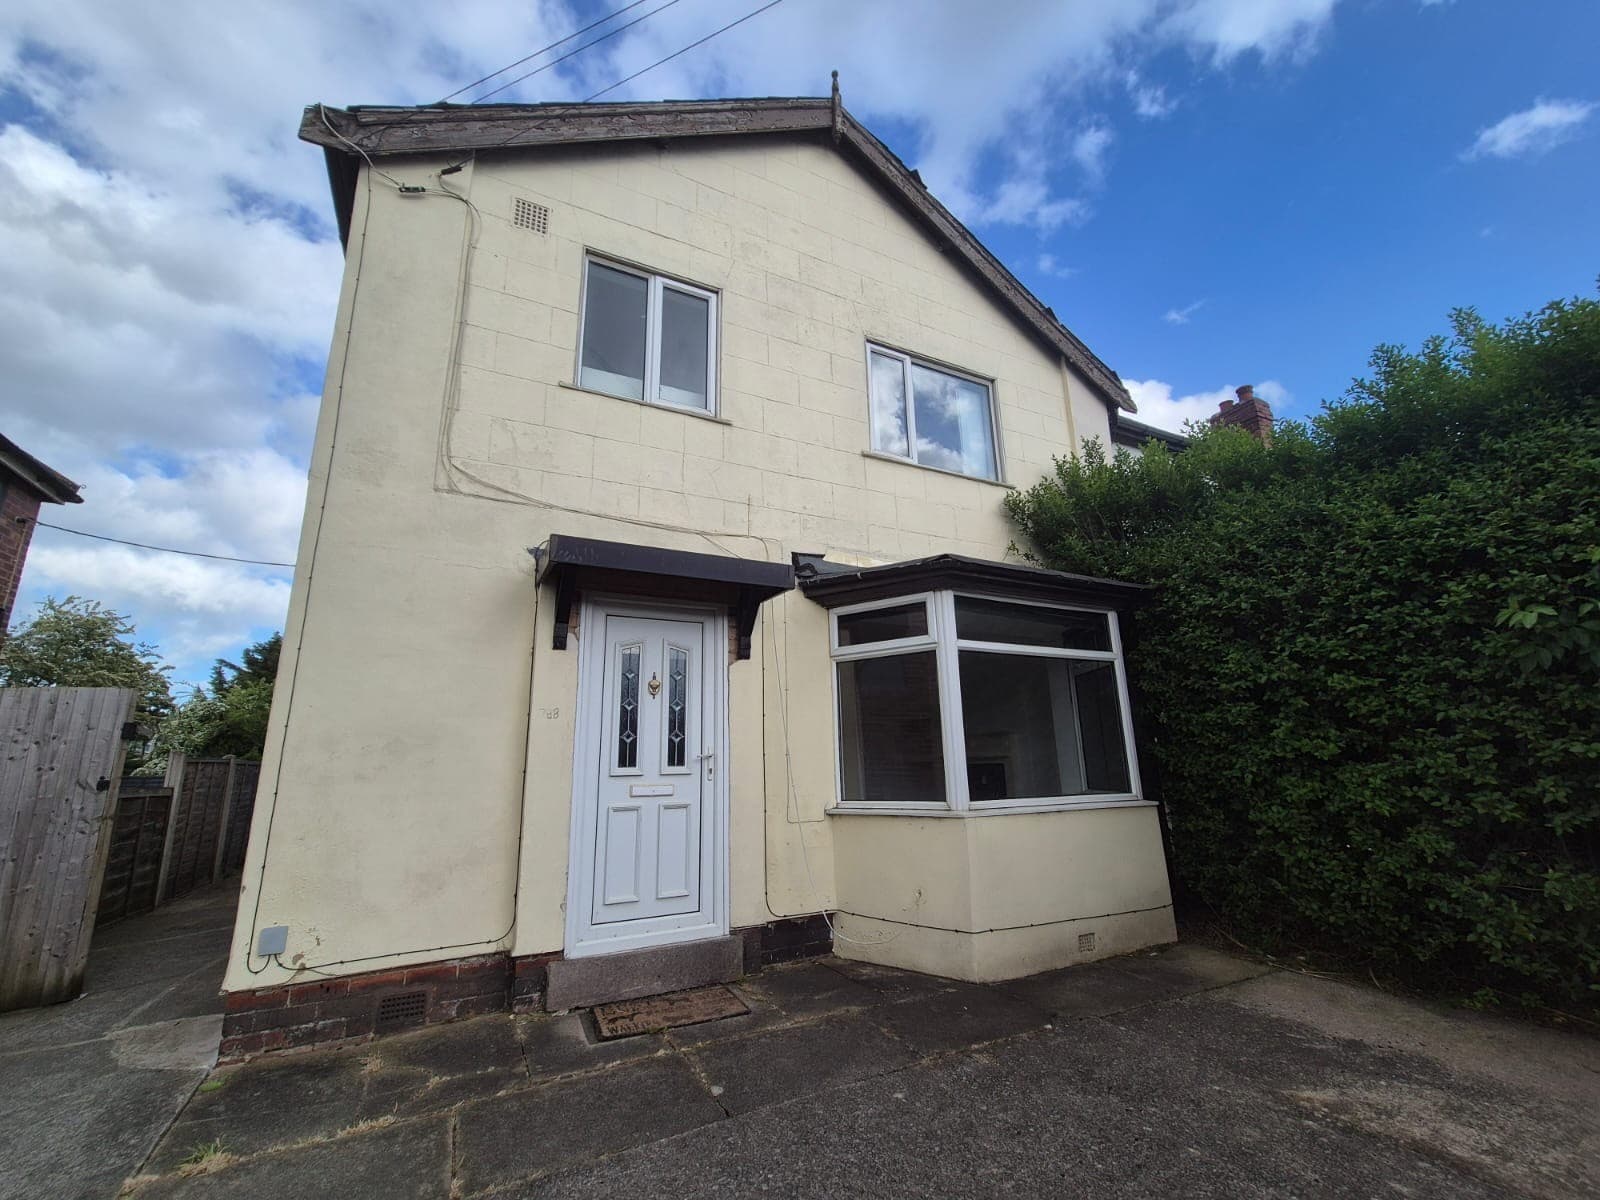
84 Poole Crescent, Leeds, LS15 7LU
UPRN:72159027End Terrace House3 bedsBuilt 1930-1949
FreeholdCouncil Tax: Band AEPC: C (69)
Data freshness:Listing· freshListing: fresh, refreshed 2d ago (2026-10-21T04:00:02.931607+00:00)Planning· 4mo agoPlanning: stale, refreshed 4mo ago (2026-07-10T08:11:29.761902+00:00)EPC· 4mo agoEPC: stale, refreshed 4mo ago (2026-07-01T02:04:50.057738+00:00)Risk· 2y agoRisk: stale, refreshed 2y ago (2024-12-31T00:00:00+00:00)Crime· freshCrime: fresh, refreshed 6d ago (2026-10-17T11:20:03.253738+00:00)Schools· 3mo agoSchools: ageing, refreshed 3mo ago (2026-08-06T07:49:20.947654+00:00)Amenities· 1mo agoAmenities: ageing, refreshed 1mo ago (2026-09-23T00:00:00+00:00)Area· Census 2021Area: static reference data (Census 2021); authoritative and does not refresh
HP Score
71
/ 100
Mixed
Verdict
today
- Verdict: INVESTIGATE, on a scale of Buy, Investigate, Avoid.
Mixed signals - investigate
Evidence
19 of 21 sourcesSale Estimate
£193,000
£183k - £202kHigh
Estimate
£193k
Range
£183k – £202k
Rent Estimate (pcm)
£950
£900 - £1k
Monthly
£950
Yield
9.91%
Verdict
Derived from HomePortfolio scores
84 Poole Crescent earns an INVESTIGATE rating with HP Score 71/100. Investment score 58/100 reflects moderate fundamentals. Crime intensity is low. Walkability is good (77/100). Flood risk is not assessed: check the Environment Agency long-term flood map before offering. Tenure is freehold. Every figure here comes from the live HomePortfolio API; anything it does not publish is left out.
Key SourcesEPC RegisterPortal listingsOfcom Connected NationsOfcom mobile coverageMarket estimates (third-party AVM)HM Land Registry sales matched to addressDefra strategic noise mapping, England Round 4 (Contains Defra data © Crown copyright and database right 2023-2024, Open Government Licence v3.0)Walk ScoreONS Census 2021Police.ukHM Land Registry company ownershipHM Land Registry covenantsHM Land Registry Price PaidPlanIt / council planning portalsOverture Maps PlacesOfsted / DfE GIAS
71
HP Score
71/ 100
Mixed
58
Investment Score
58/ 100
Moderate
33
Crime Score
33/ 100
Moderate
77
Walkability
77/ 100
High
Transit & Bike
Transit 37Bike 64
Walk Score, out of 100
Valuation & Market
Sale Estimate£193,000
Rent Estimate (pcm)£950
Gross Yield9.91%
1y Growth-
3y Growth+1.0%
5y Growth+2.2%
10y Growth+4.5%
Last Sold Price£127,000 (2019-05-16)
Risk Overview
- Flood RiskUnknown
- SubsidenceLow
- RadonLow
- MiningUnknown
- LandslideLow
- Air QualityLow
- NoiseLow
Planning Activity
Recent Apps
0LS15 7LU
Approval Rate
-12mo
Development
low
- Pending26/05555/FUVariation of conditions 2 (approved plans), 8 (statement of construction practice), and 9 (use of lift) and removal of condition 4 (external seating and use) of previously approved planning application 26/01156/FU (Change of use of former bank (Use Class E(c)) to a bar (sui generis), including internal and external alterations) for minor amendments to the approved plans; to allow use of external areas at specific times; to reword conditions 8 and 9
- Pending26/05605/FUPart retrospective change of use to form first and second floor apartment and ground floor offices; associated creation of door to front
- Pending26/05483/CONDConsent agreement or approval of Condition 21, 25 of Planning Application 24/02842/FU
Ownership
- Corporate Ownership61.7%
- Overseas OwnershipNo
- Lease Term Remaining-
- CovenantsRestrictive
- Lease TypeFreehold
- Last Ownership Change2019-05-16
- SourceLand Registry
Connectivity
Broadband (Standard)
17 Mbps
Mobile 4G/5G Coverage
EEThreeO2Vodafone
EV Charger
-
PTAL Rating
-
Area Profile
Median EarningsLocal authority£31,679
Population Density4,400 /km²
Owner Occupied41%
Age Distribution
0-15 21%16-64 62%65+ 17%
Schools Nearby
- Cross Gates Primary School0.1 miGood
- Parklands Primary School0.5 miReport card2026
Ofsted no longer awards a single overall grade.
- Templenewsam Halton Primary School0.6 miGood
- Leeds East Academy0.6 miArea grades2024
Inspected after Ofsted withdrew the single overall grade.
3 of 14 nearby schools with published figures were oversubscribed in 2026 - demand, not a catchment.
Comparables
- 85 Poole Crescent-£205k-
- 62 Poole Crescent-£185k-
- 77 Poole Crescent-£180k-
- 70 Poole Crescent-£168k-